
In March 2026, a bank made a payment it didn’t manually approve. Banco Santander and Mastercard completed what both companies call Europe’s first live end-to-end payment executed by an AI agent — processed through Santander’s live payments infrastructure inside a regulated banking framework (Santander, 2 March 2026). Just as important is what came after: Santander explicitly called it a controlled pilot, not a commercial rollout.
That contrast — the milestone, followed by the disclaimer — is the real story of AI agents in finance in 2026. The technology has genuinely left the lab. But it’s moving at two very different speeds: fast for internal, low-risk operations (fraud, onboarding, customer support), and carefully for anything that touches actual money.
This guide separates what’s really deployed from what’s being announced, gives you the numbers that hold up under scrutiny, and walks through the regulatory dates that will force decisions regardless of how anyone feels about it.
What an AI agent actually is in finance
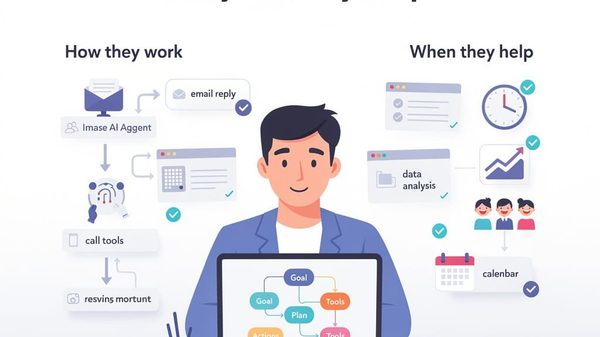
A chatbot tells you your balance. An agent can, within defined limits, act on your account. The 2026 Global AI in Financial Services report from the Cambridge Centre for Alternative Finance defines agentic AI as “systems that pursue objectives through autonomous, multi-step sequences of actions” — decomposing a goal, calling tools and APIs, observing results, and revising (CCAF, 28 April 2026).
That difference matters because almost every article on this topic blurs the two. We covered the shift from chatbots to assistants here — but the leap from “talking to a bot” to “letting software act on your account” is the whole story. The open question in 2026 isn’t whether agents can do the work. It’s what they’re allowed to do without a human.
What’s actually deployed in 2026
Every row in this table is a primary-source announcement with a date you can check:
| Who | What | Date | Status |
|---|---|---|---|
| Santander + Mastercard | First live end-to-end payment executed by an AI agent via Mastercard Agent Pay, run on Santander’s live rails (source) | Mar 2026 | Pilot |
| Sygnum (Swiss bank) | AI agent executed live multi-step on-chain transactions (stablecoin transfers, swaps, lending) via an MCP server; client signs every action, private keys never leave the device (source) | May 2026 | Pilot |
| OCBC (Singapore) | HELIOS agentic platform: private-bank account opening cut from a ~6-week industry median to 15 business days; Source-of-Wealth prep from 10 days to 1 hour (source) | Jul 2026 | Production |
| FIS + Anthropic | Financial Crimes AI Agent, compressing AML investigations from hours to minutes; BMO and Amalgamated Bank in development, GA planned H2 2026 (source) | May 2026 | Development |
| European digital bank (via Gradient Labs) | AI agent handled 280,000+ support conversations for ~500,000 customers at 98% QA — above the bank’s 95% human benchmark (case study) | 2025–26 | Production |
Notice the pattern: the deployments closest to real money are pilots; the ones inside back-office operations are in production. That split is the shape of the entire industry right now — one we’ve examined in detail in The Automation Revolution: How AI Is Rewriting the Rules of Banking and Markets.
Three areas where agents are already producing measurable results
1. Financial crime and AML. This is the clearest win. U.S. financial institutions alone spend an estimated $35–40 billion a year on AML operations, with the UN estimating around $2 trillion in illicit flows annually (figures cited in the FIS announcement). Vendors report dramatic compression — FIS says hours to minutes; Cleafy claims under four minutes versus more than four hours manually; INETCO reports 10–30 minutes down to ~20 seconds. Those last two are vendor claims, so treat them as directionally plausible rather than gospel. But the direction is consistent across competing companies, which is about as good as industry evidence gets. The flip side of that speed is worth reading: how fraudsters and hackers use AI against the financial system.
2. Onboarding and KYC. OCBC’s numbers are the strongest primary-source example: account opening in 15 business days against a ~6-week industry median, with most due diligence done before a relationship manager ever contacts the customer (OCBC, 29 July 2026). Compliance stays accountable — the agent front-loads the work; humans own the decision.
3. Customer operations. The Gradient Labs deployment shows what scale looks like: hundreds of thousands of conversations, quality above the bank’s own human teams, and 9 million real-time guardrail checks. Every reply screened before it reaches a customer. This is the “human-in-the-loop, but the loop is fast” model that’s actually working in 2026 — the same logic behind how NVIDIA uses agents to automate HR, finance and marketing workflows.
Where it breaks
The uncomfortable part of the 2026 data is the governance gap. Deloitte’s State of AI in Financial Services report found 71% of financial-services firms plan to deploy agentic AI within two years — but only 23% have a mature governance model for autonomous agents. That’s a race where the car is faster than the brakes.
The Cambridge report adds a second, quieter problem: regulators are behind. Only 28% of surveyed regulators have adopted agentic AI in any form, versus 52% of the industry they supervise (CCAF, 2026). And 51% of industry respondents name “loss of human oversight” among their top three AI risks. When the supervised move faster than the supervisors, the rulebook eventually gets written in reaction to an event — not before it. If that scenario worries you, our analysis of whether AI algorithms could trigger the next financial crisis looks at exactly that failure mode.
There’s also a technical constraint that polite coverage skips: hallucination and reproducibility. The Amundi Research Center’s 2026 survey concludes hallucination is often a more limiting factor than architecture — which is why human verification remains mandatory in current financial deployments, full stop. It’s a specific case of the broader common-sense gap: the model can’t reliably tell you when it’s wrong.
The regulatory calendar that will force your hand
The “AI Act was delayed” headlines are half true — and the half that’s wrong is the half that matters. The EU’s AI Act has been in force since 1 August 2024, and the Digital Omnibus amendments (in force 27 July 2026) moved the high-risk deadlines back — but not the transparency rules:
| Obligation | Deadline |
|---|---|
| Transparency (Art. 50): disclose when customers interact with AI; machine-readable marking of AI-generated content | 2 Aug 2026 — unchanged |
| Content-marking grace period (shortened from 6 months to 3) | 2 Dec 2026 |
| High-risk AI in finance (credit scoring, insurance pricing, Annex III) | 2 Dec 2027 |
| High-risk AI in regulated products (Annex I) | 2 Aug 2028 |
| New prohibited practice under Art. 5 | 2 Dec 2026 |
For finance specifically: credit scoring and life/health insurance pricing are classified high-risk under Annex III, points 5(b) and 5(c). The fraud-detection carve-out exists, but if your system profiles people, the exception almost certainly doesn’t save you.
Two more regulatory pieces every institution should have on its radar:
- FINRA’s 2026 Annual Regulatory Oversight Report flags AI agents “acting beyond the user’s intended scope” as a core risk and points firms toward human-in-the-loop checkpoints before any agent gets transaction authority.
- MAS published SAFR — Safeguards for Agentic Finance at Runtime — in July 2026, a framework for how agent actions get authorized, when human oversight kicks in, and what gets recorded at the point of every decision (MAS, 3 July 2026). Singapore isn’t waiting; it’s writing the playbook.
Governance isn’t a tax on innovation here — it’s the thing that lets you scale without getting owned by your own system. IBM’s argument on that point is worth reading before you plan the next pilot.
What a financial institution should actually do
Based on the evidence above, not the marketing:
1. Inventory first, classify second. You can’t govern what you haven’t listed. Most banks can’t enumerate every AI system touching a regulated activity today — your DORA ICT asset register is the right starting point.
2. Treat the August 2026 transparency deadline as real. Disclosure that a customer is talking to an AI is a copy change; content marking is an engineering change. Both are small next to high-risk conformity, and both are due now.
3. Separate proposal from execution. The agent proposes an action, but a deterministic policy engine — not the model — authorizes it. Value limits, counterparty rules and compliance checks live in deterministic code, not in a probability distribution. A prompt-injected agent can then generate bad proposals, but it can’t move money.
4. Assign autonomy tiers. Not every agent needs the same authority. Fraud alerts an analyst reviews: high autonomy. Drafting a reply a human approves: high autonomy. Initiating a wire transfer: near zero, until the control stack is boring and auditable.
5. Design for the human-in-the-loop, don’t just tolerate it. The successful 2026 deployments aren’t the ones that removed humans. They’re the ones that made the human’s job ten times faster — a 4-hour investigation becomes 4 minutes of review; a 6-hour first response becomes a 4-minute one. That’s the model that works, and it’s the theme running through how AI is rewriting banking and market operations across the industry.
What this means for you, honestly
If you run a bank or work in compliance: the back office is where the return is — AML, onboarding, disputes. Don’t start with payments. The people moving first on payments are doing it as pilots, with lawyers at the table, for a reason.
If you’re at a fintech: you have a structural advantage — fintechs lead incumbents in agentic adoption (57% vs 45%, per CCAF). But the lead only compounds if governance comes with it. On the trading side, we’ve compared the best AI tools for forex traders in 2026 and looked at whether AI can actually predict the stock market — useful reading if your roadmap leans toward markets rather than banking ops.
If you’re a customer: the good news is 2026’s agents are being built with you in the loop — Sygnum’s model has you signing every action, with private keys on your own device. The bad news is the industry is scaling faster than oversight. The single most useful question to ask your bank: “When I talk to an AI, is that disclosed, and what can it do without a human?” From August 2026, in the EU, they legally have to answer the first half.
The bottom line
The 2026 story of AI agents in finance isn’t “the robots took over” and it isn’t “all hype.” It’s that a narrow slice of the industry — fraud, onboarding, support — has genuinely crossed into production with numbers that survive scrutiny, while the money-moving applications sit carefully in pilot mode, and the governance model is roughly two years behind the deployment plans.
The institutions that win this era won’t be the ones with the most impressive demos. They’ll be the ones that built the control stack first — inventory, transparency, deterministic limits, autonomy tiers, and humans who actually have time to think because the agent did the four hours of legwork.

Independent technology writer focused on artificial intelligence, emerging technologies, and digital innovation. Covers AI applications in sports, productivity, and online business.